November 5, 2026, 8:00 a.m. (JST)
[Japan]
Issuer
Plans That Reduce the Risk of Fraud Member site authentication is also possible with the same simple steps
UniPasskey offers a variety of plans; in this article, we’ll explain the Issuer Plan and the Call Center Plan.
There are various 3-D Secure mechanisms, such as the SPC (Secure Payment Confirmation) method, the OOB (Out-of-Band) method, and brand-specific implementations. UniPasskey uses the OOB mechanism. We have developed a service that performs authentication via a channel separate from the payment screen and returns the results.We implement both types of authentication together. With traditional 3-D Secure authentication using a passkey, users undergo fingerprint or facial recognition when making a purchase with their card. UniPasskey goes beyond that—we’ve created a system that allows this passkey authentication to be performed within the same framework, including access to the Issuer’s member site.
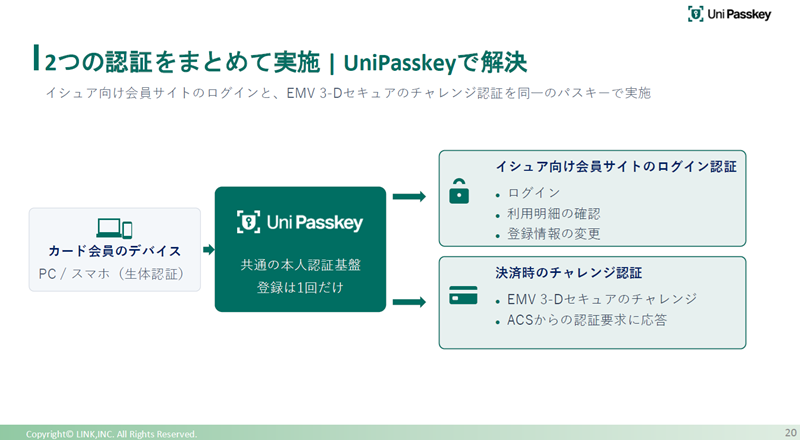
Earlier, I explained the risk of unauthorized access to a member page protected by an ID and password, where registered information could be altered. We believe that requiring passkey authentication during login—ensuring only the account holder can access the site—significantly reduces this risk, which is why we are moving forward with this plan.
The login authentication process works as follows: When a cardmember visits a website and requests to log in, a passkey request is triggered. The server sends a challenge code; the cardmember then authenticates themselves on their device using a fingerprint or facial recognition. The login is completed when the device signs the challenge using its private key and sends it back. Biometric data and private keys are never sent to the server.
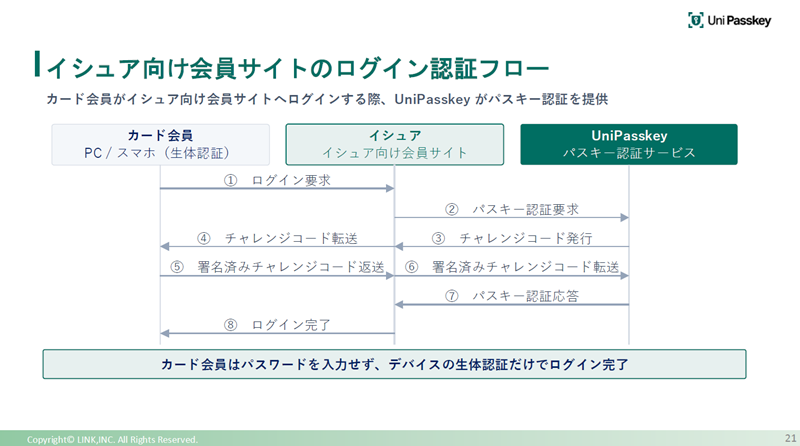
A good example of this is the login process at securities firms. Many securities firms are increasingly adopting passkey authentication for logins, and this is the kind of process we envision.
Regarding payments, the same passkey used for login can be employed to process credit card payments through the same exchange. The benefit for issuers is the ability to prevent fraud before it occurs and reduce the burden of losses. Since identity theft becomes more difficult, losses can be reduced even further compared to the current situation. We believe this is one benefit that issuers can enjoy.
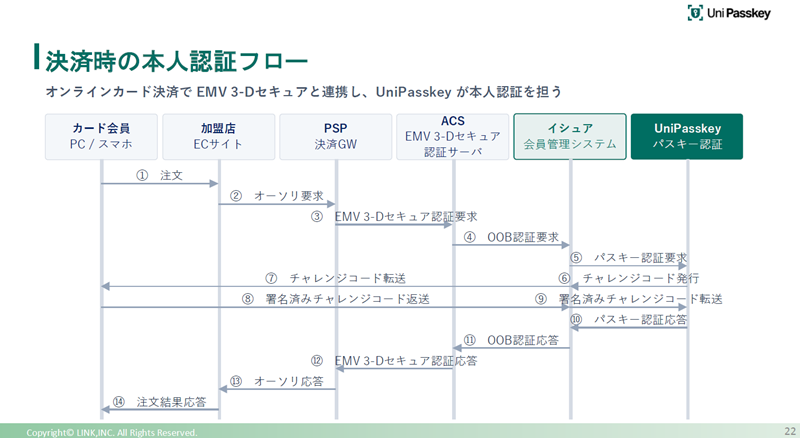
Regarding Authorization Rates, as fraudulent transactions decrease, so too will transaction declines due to risk concerns, leading to an expected improvement in Authorization Rates. This will also contribute to higher customer satisfaction.
Biometric authentication significantly enhances the cardholder experience. Previously, users had to enter a one-time password sent to them. With biometric authentication, authentication is immediate, and the payment is completed right away.
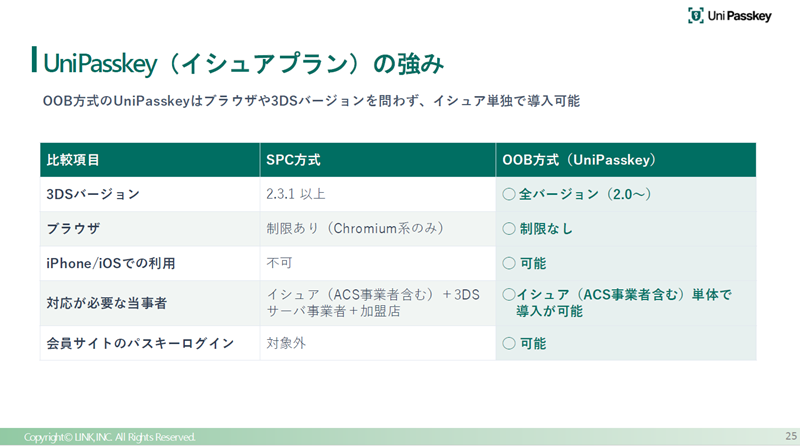
A key strength of the Issuer Plan is its adoption of the OOB (Out-of-Band) method. The SPC method has limitations regarding the usage environment; for example, supported browsers are currently limited to Chrome-based browsers, and it cannot be used on iOS as-is. With the OOB method, there are fewer constraints related to browsers or operating systems, enabling multi-device compatibility.
UniPasskey Call Center Plan
Freedom from the Stress of Identity Verification
When we announced the Issuer Plan in a press release, we received inquiries from customers who wanted to “use it in different ways.” One such example is the Call Center Plan. We are currently developing this service to explore how UniPasskey can be utilized in telephone scenarios.
We provide a cloud-based IP-PBX service called BIZTEL, and we received requests from these customers to make identity verification more rigorous and convenient when handling calls at call centers.
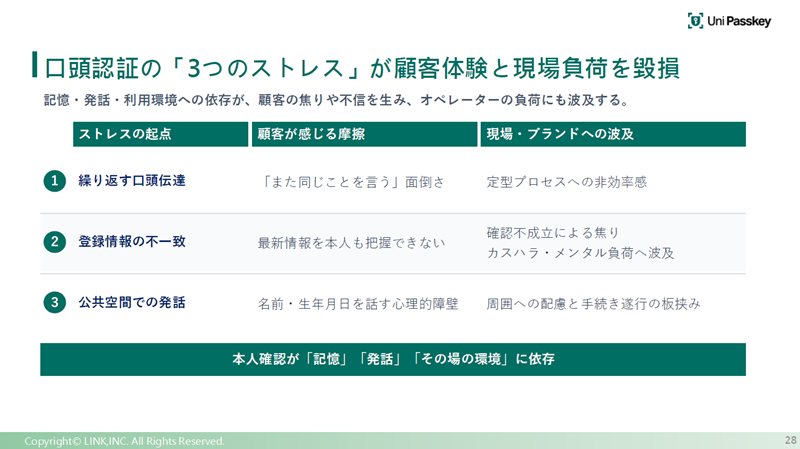
The UniPasskey Call Center Plan eliminates three major sources of stress encountered during phone calls.
First, when verifying a customer’s identity, agents are often required to ask for various details such as date of birth, address, and phone number. Using UniPasskey in a call center setting eliminates these repetitive questions. For example, when a customer calls a credit card company, the agent views it as just another call and ends up asking the same questions every time. With UniPasskey, this process can be completed in a single step using fingerprint or facial recognition.
Second is the issue of mismatched registration information. It’s not uncommon for address changes to not be updated immediately with credit card companies after moving. This can result in authentication failures due to discrepancies between the registered information and your current details. With UniPasskey, authentication failures caused by such mismatches are eliminated.
The third issue is speaking in public spaces.You won’t always be making calls from home. For example, when you need to make a call at a city hall or a bank, you’d have to say your name and date of birth out loud, creating the risk that bystanders might overhear your personal information. Using this PassKey eliminates that risk. Since you don’t have to speak, that problem disappears. These are the three sources of stress we’ve identified, though there may be others.
The current system of identity verification drives up call duration and operational costs.Call centers strictly calculate the time an operator spends on each call, and supervisors are constantly looking for ways to reduce that time by even a single second to handle more calls. Identity verification typically takes between 45 and 90 seconds, but implementing UniPasskey can significantly reduce this time.
Since UniPasskey completes identity verification using fingerprint or facial recognition, it can reduce the time required—which previously took up to 90 seconds—to about 10 seconds. This significantly reduces the burden on both operators and customers.
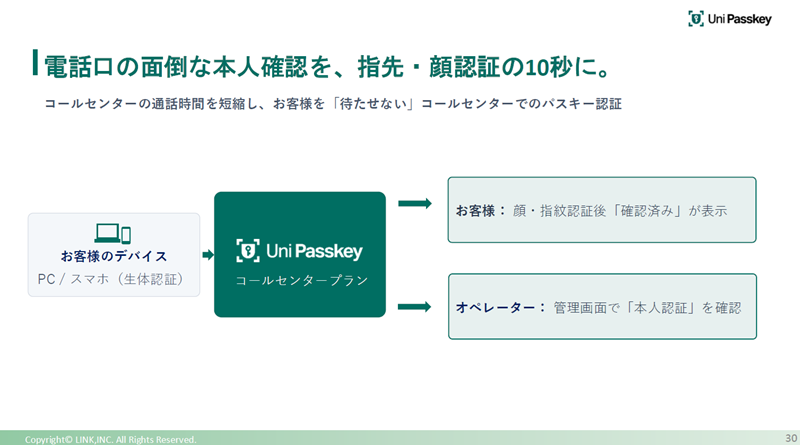
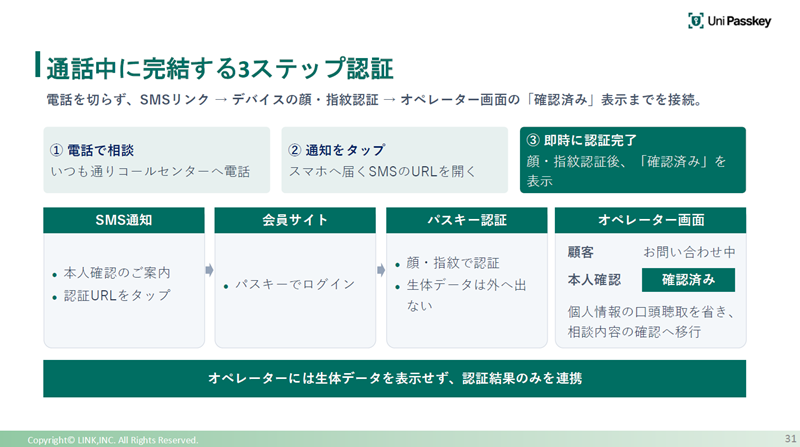
UniPasskey uses a three-step authentication process, sending an SMS to the customer during the call. The system is designed so that when the customer clicks the URL and then clicks on the screen that appears, the biometric authentication process begins. Once authentication is completed, a notification is sent to the operator confirming that authentication is complete. This mechanism is built into UniPasskey.As long as the operator can send a URL to the customer via SMS and the customer has an internet-enabled device, this UniPasskey call center plan can be used regardless of the call system in place.
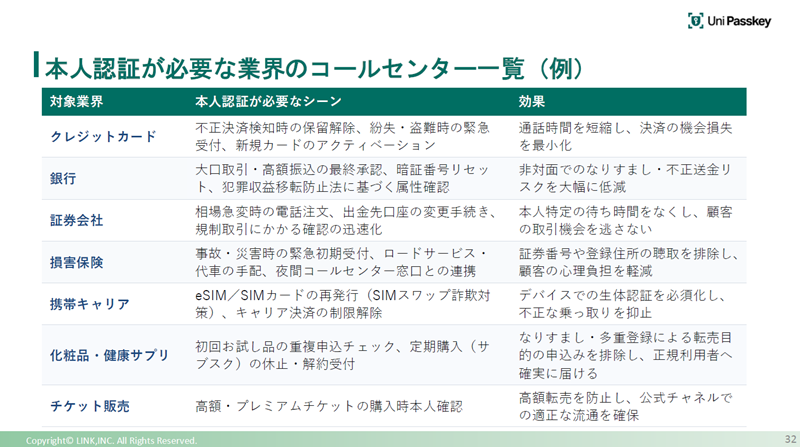
In addition to
identity verification for credit cards, banks, and securities firms, it is effective for call centers handling auto accident scenes at property and casualty insurance companies.
We considered which types of call centers could benefit from this solution. Since our business has grown through credit card security, we believe credit card companies will be the primary initial target. Second are banks, followed by securities firms; we expect to see widespread adoption among the financial industry.
Another sector is property and casualty insurance. For example, when receiving reports of car accidents, call centers verify the caller’s identity by confirming details such as their date of birth.Other examples include inquiries to mobile carriers and ticket sales—any situation requiring authentication. Identity verification is frequently used in these scenarios, and we believe that companies operating such call centers can use UniPasskey to enhance the customer experience and reduce response times on the call center side.
We have also received inquiries from e-commerce platform providers who wish to introduce UniPasskey as an option for their own services. They asked, “Does it have to be a card?” But since e-commerce platforms also require login and Identity Verification, UniPasskey can certainly be used there as well.
To summarize, the first option is the Issuer Plan. A key feature of the Issuer Plan is that it allows services to be implemented using the same biometric authentication and passkey mechanisms for both logging into the My Page and making payments.Second is the Call Center Plan. This enables the use of PassKey for customer identity verification during phone calls at call centers. We believe PassKey can be utilized in various other scenarios as well, and we look forward to expanding the range of supported use cases through discussions with you all in the future.
Regarding service development, we build our server infrastructure and applications with security in mind. For example, we ensure our service is compliant with PCI DSS—the credit card security standard—as a matter of course, so you can use it with confidence.
In addition to the Issuer Plan and Call Center Plan I’ve introduced today, if you have any ideas about other scenarios where PassKey could be used, please feel free to reach out to us. We believe this will contribute to the further development of our service, so we would greatly appreciate your input.
Please direct any inquiries to the contact information below. That concludes my presentation. Thank you very much for your attention.
■Contact
Information  Link
Co., Ltd. 107-0061
2-14-4
Kita-Aoyama, Minato-ku, Tokyo Argyle Aoyama, 14th
Floor TEL: 03-6704-9090
https://pcireadycloud.com/
Inquiries: https://pcireadycloud.com/guest/