October 6, 2026, 8:00 a.m. (JST)
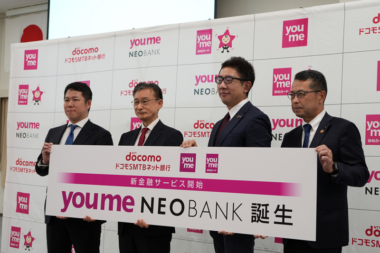
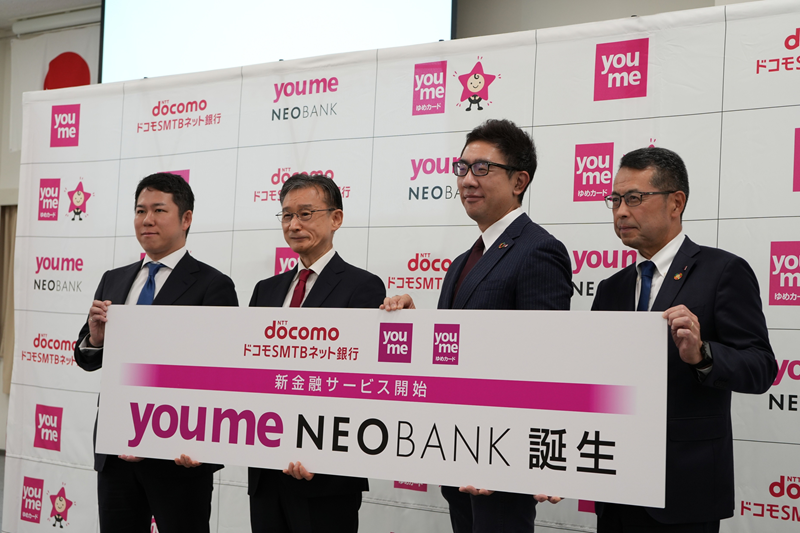
[Japan] Docomo SMTB Net Bank (Tokyo, Japan) and Izumi (Hiroshima) held a press briefing on September 30, 2026. Together with Yume Card (Hiroshima), which provides financial services such as credit cards and electronic money within the Izumi Group,announced that they had launched “Yume NEOBANK,” a new financial service utilizing Docomo SMTB Net Bank’s BaaS capabilities, on October 5, 2026.
Banking Services, the Yume App, and Yume Card Integrate
Auto-Top-Up Now Available for “Yumeka” Electronic Money
The press briefing was attended by Mr. Noriaki Maruyama, President and CEO of Docomo SMTB Net Bank; Mr. Tomoyuki Naomi, Senior Managing Executive Officer and Head of the 10X Business Division; Mr. Shigeki Machida, President and CEO of Izumi; and Mr. Kazuya Iwaki, President and CEO of Yume Card, who introduced the collaborative initiatives.
The Izumi Group operates “Yume Town,” “Yume Mart,” and “Yume Mall” stores primarily in the Chugoku, Shikoku, and Kyushu regions. The company aims to become a comprehensive lifestyle industry in the region, particularly in Western Japan, and strives to contribute to the creation of livable, vibrant communities.
“Yume NEOBANK” reportedly offers several permanent programs designed to appeal to Izumi customers and others.
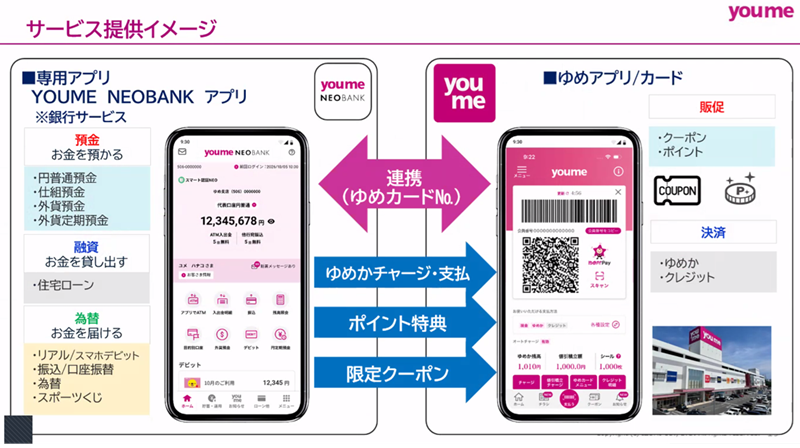
A key feature of the service is that everything—from opening an account to banking transactions such as deposits and transfers—can be completed entirely via a smartphone app. By integrating with the “Yumeka” e-money service and the “Yume App,” the company hopes customers will experience tangible benefits in various scenarios, including “saving,” “spending,” and “borrowing.”
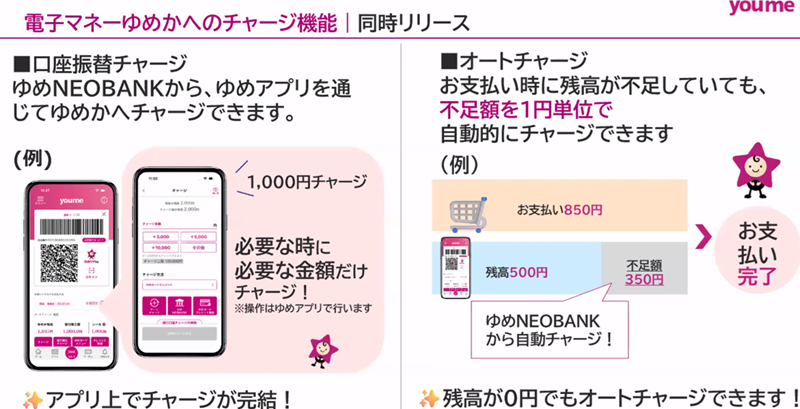
Users can top up the prepaid e-money “Yumeka” via their smartphones from Yume NEOBANK. Additionally, with Auto-Top-Up, even if the balance is insufficient at the time of payment, the shortfall can be automatically topped up in increments of 1 yen. Since Auto-Top-Up works even when the balance is zero, it reduces the hassle of manually topping up.
Rewards
for Top-Ups and Setting Up Credit Withdrawal Accounts App Coupons Based on Yen Deposit Balances
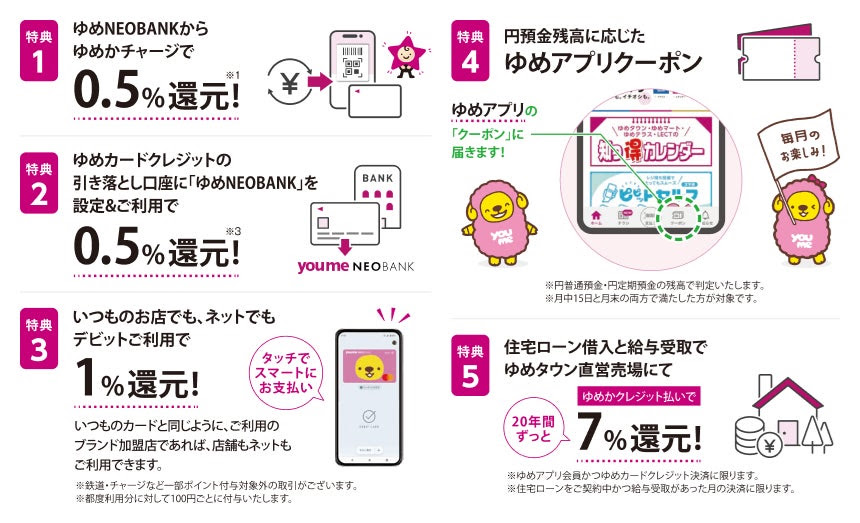
Furthermore, users receive a 0.5% rebate on the amount charged to “Yumeka” from Yume NEOBANK.The reward accumulates at a rate of 5 yen per 1,000 yen. Furthermore, if you set “Yume NEOBANK” as the withdrawal account for the “Yume Card” credit card issued by Yume Card and use it, you’ll receive a 0.5% cashback (in both cases, this applies to top-ups of up to 50,000 yen per month, equivalent to 250 yen in rewards).In other words, combining the basic “Yumeka” benefit with the credit card benefit results in a maximum cashback of 2% or 6% (on “5x Points Days”).
In addition, using the Docomo SMTB Net Bank debit card earns a 1% cashback. Furthermore, “Yume App Coupons” corresponding to the amount of yen deposits are delivered to the Yume App. Additionally, customers receive a 7% cashback at Yume Town-operated stores when taking out a mortgage or having their salary deposited there.
As a key feature of the partnership between the two companies, they highlighted the ability to provide banking services—including “deposits,” “loans,” and “foreign exchange”—by leveraging BaaS.Users can deposit and withdraw funds at Seven Bank and Lawson Bank ATMs nationwide via the app (up to 5 free ATM transactions and 5 free transfer transactions per month).
Izumi: Expanding
Touchpoints in the Ecosystem as a Third Pillar of Revenue What Are the Goals and Value Proposition of the Service?
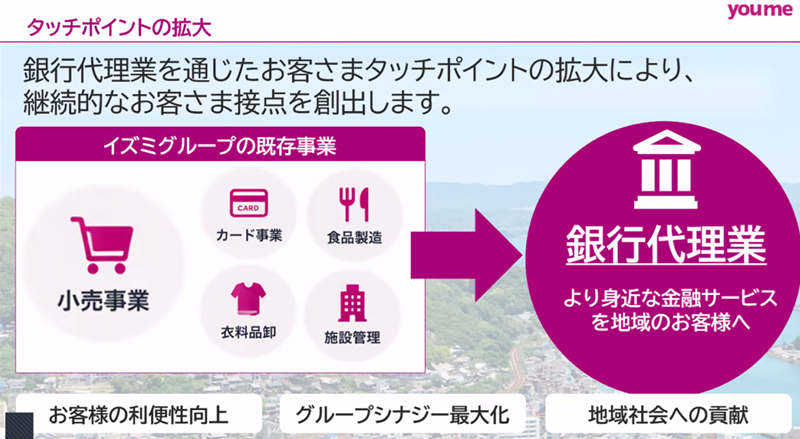
In Izumi’s Third Mid-Term Management Plan (2026–2030), strengthening retail-related and new businesses is listed as one of the core strategic policies.As its third revenue pillar, the company plans to provide and expand its financial services, food and beverage offerings, and points Ecosystem. As part of this initiative, Izumi will enter the banking agency business through a joint venture with Yume Card utilizing BaaS. By expanding user touchpoints through this banking agency business, the company aims to create ongoing customer engagement.Mr. Machida stated, “We will provide these services to both our current and new customers.” By offering financial services, the company aims not only to improve customer convenience but also to maximize group synergies and contribute to the local community.
Their partner, Docomo SMTB Net Bank, has launched a business that provides highly flexible financial functions to operating companies based on its own track record, becoming “Japan’s largest financial institution for BaaS” (Mr. Maruyama). As of September 30, the number of partner companies stands at 28, offering 29 services.
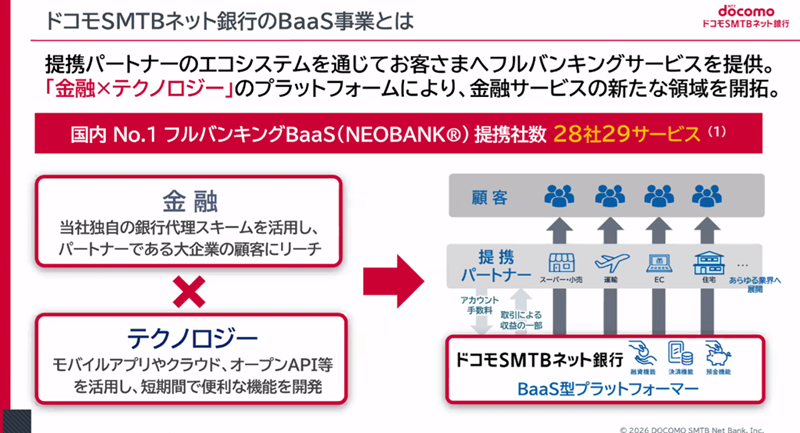
The bank has also become one of the largest players in the mortgage market in Japan, and Mr. Maruyama notes, “Our strength lies in areas where we are closely connected to real customers.”The company reportedly aims to become the primary bank within each Ecosystem it serves. This marks its first collaboration with the Izumi Group in the Chugoku and Shikoku regions. Mr. Maruyama expressed his enthusiasm, stating, “Partnering with supermarkets—which are closer to everyday life and more closely integrated into daily routines than banks—contributes to our primary bank strategy and provides an opportunity to deliver the best financial services.”
Docomo SMTB Net Bank offers more than 300 financial functions and undertakes contract development of the actual apps required by partner companies—such as QR payment platforms and savings apps. The company also works closely with partner firms to solve their challenges and is committed to providing satisfying financial services and customer experiences.
Both companies have been preparing to launch the service since last year. Izumi views this as an initiative to increase touchpoints within a new Ecosystem.While Yumeka usage has traditionally been concentrated among people in their 30s and 40s, the company plans to extend its value to users in their 20s as well. Mr. Machida stated, “We have Yume Card members, but there is an issue with the cashless function—specifically, the inability to set up auto-recharge. For younger users, the ability to recharge quickly is a key value proposition and a key service feature.”